Ready for a Better Car? Compare the Upgrade With What You Pay Now
Plan your next car using the payment you already make. Compare trade payoff, insurance, fuel, maintenance and the full cost of a better-fitting vehicle.
Published October 3, 2026
Watch the guide
A Better Car Starts With the Budget You Already Have
Your next car should make daily life better. Maybe you need more space, a smoother commute, or fewer unexpected service visits. Start with the budget you already have. If you still owe on your car, you are already making payments. Imagine the current payment is three hundred and fifty dollars per month, and a replacement is four hundred and twenty. The payment increase is seventy dollars, not four hundred and twenty. Now add insurance, fuel, and expected service. In an illustrative example, the current car totals eight hundred dollars per month. The replacement totals seven hundred and ninety-five, because other estimated costs differ. That is not a promise of savings. It shows why the full budget matters. Check when the existing loan ends, too. Then get your payoff and trade offer. Twelve thousand dollars owed against a nine-thousand-dollar trade leaves three thousand to resolve. Ask how that amount enters the new deal. Compare the actual out-the-door price, cash due, annual percentage rate, term, and total payments. Finally, test the things you want to improve: room, visibility, comfort, and the equipment on the exact car. With the right vehicle and a complete budget, an upgrade can be a practical next step.
Your current car may still run, but it no longer makes daily life easy. Repairs keep interrupting your schedule. You need more passenger room, better visibility, or a vehicle that fits a longer commute. Buying another car can solve a real problem. The useful comparison starts with what you already spend, including the payment on the car you have.
Quick answer: Decide what the replacement needs to improve, get your current loan payoff and trade value, and compare the complete monthly budget for both vehicles. An upgrade can be worthwhile when its additional cost fits your finances and brings the reliability, space, safety equipment, or capability you need. Use real vehicle and loan quotes to choose the right replacement.
Start with the reason to upgrade
Write down the two or three changes that would make the biggest difference. Perhaps you need dependable transportation for work, room for a growing family, easier entry and exit, or the ability to carry equipment. These needs make a useful shopping filter. A car with a lower payment that misses those needs is a poor match.
Turn each priority into something you can check. Bring a child seat or measure your usual cargo. Try parking and visibility on a test drive. Confirm the safety and convenience equipment on the exact vehicle rather than assuming every trim has it. Review condition and service records. The goal is to buy transportation that works better for your life.
Compare against your existing payment
If you have a loan payoff, you may already be making monthly payments. Those payments belong in the current-car budget. Comparing a repair bill with a replacement's entire payment while leaving out the existing payment overstates the cost of upgrading.
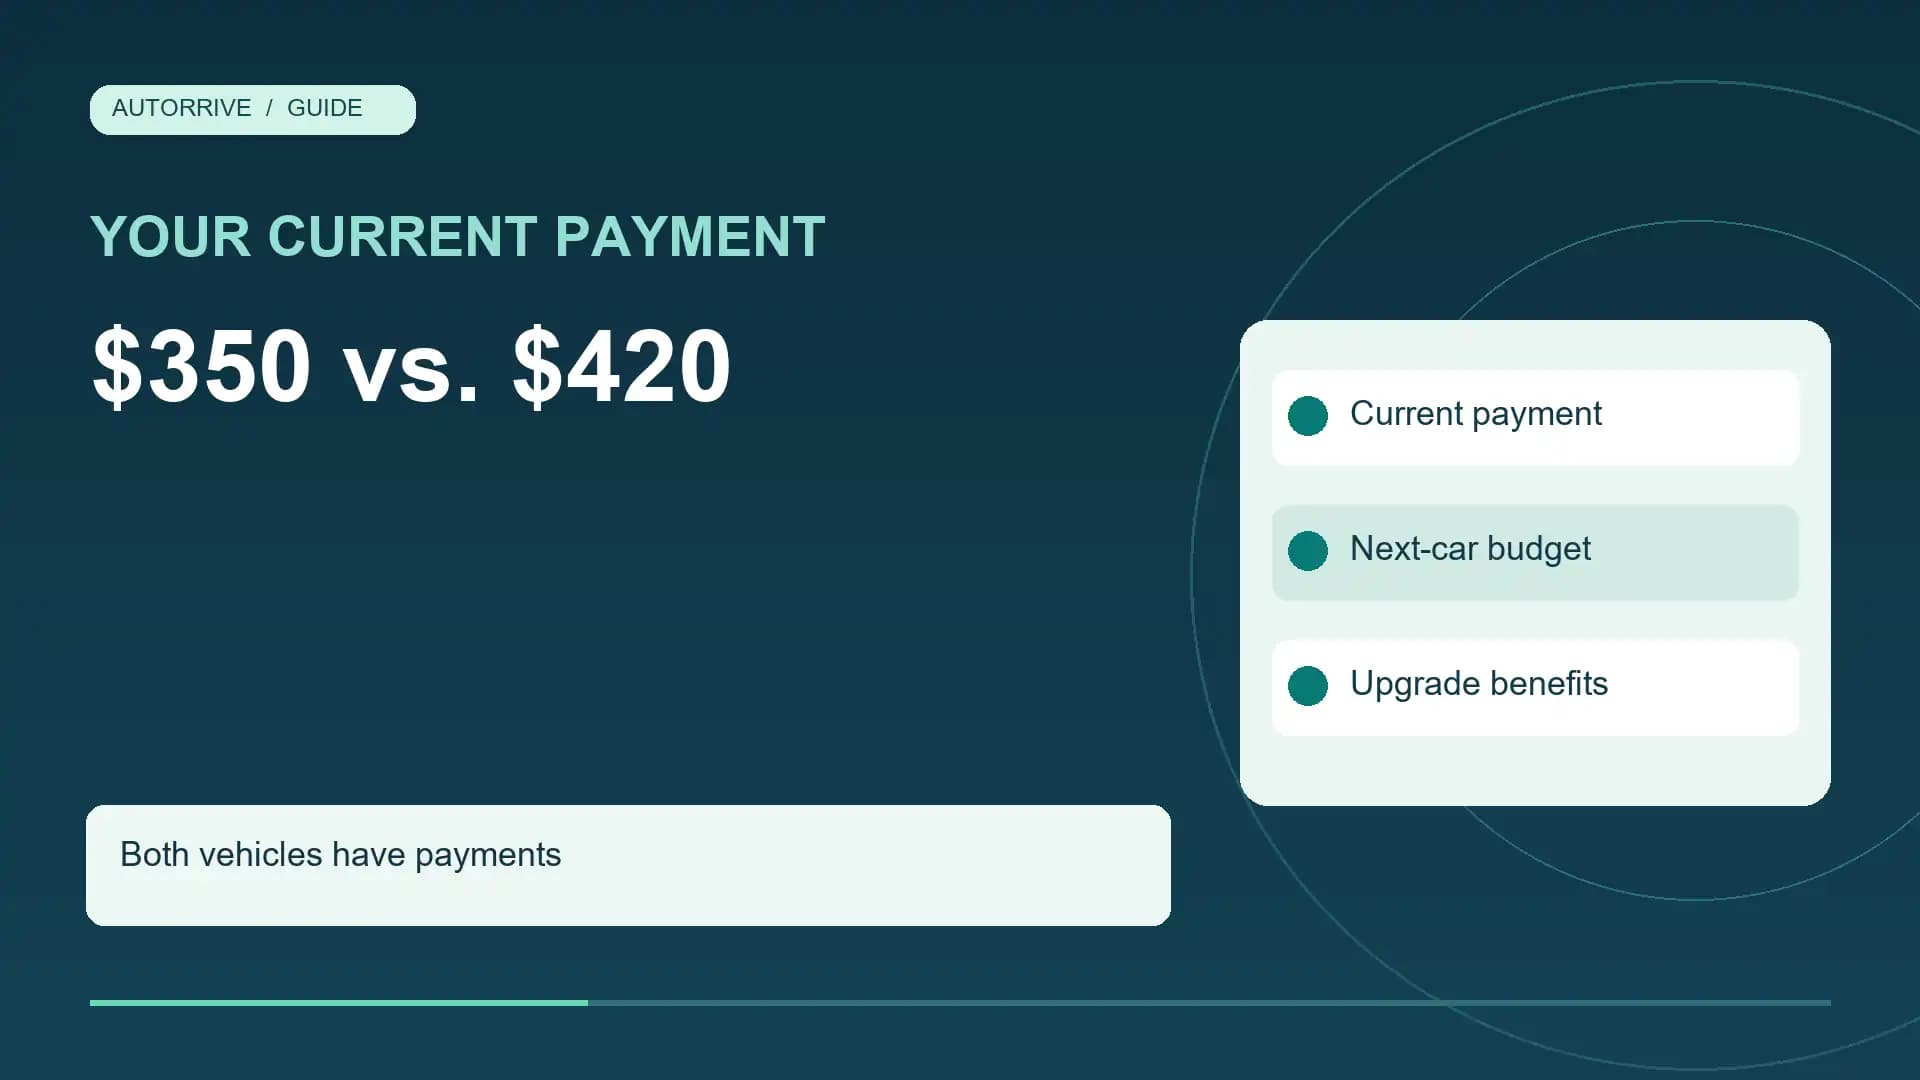
Here is an illustrative monthly cash-flow comparison, assuming both loans would remain outstanding through the next twelve months:
Compare against your existing payment
Monthly budget item
Current car
Replacement
Loan payment
$350
$420
Insurance
$120
$140
Fuel
$180
$160
Expected service and repair reserve
$150
$75
Illustrative total
$800
$795
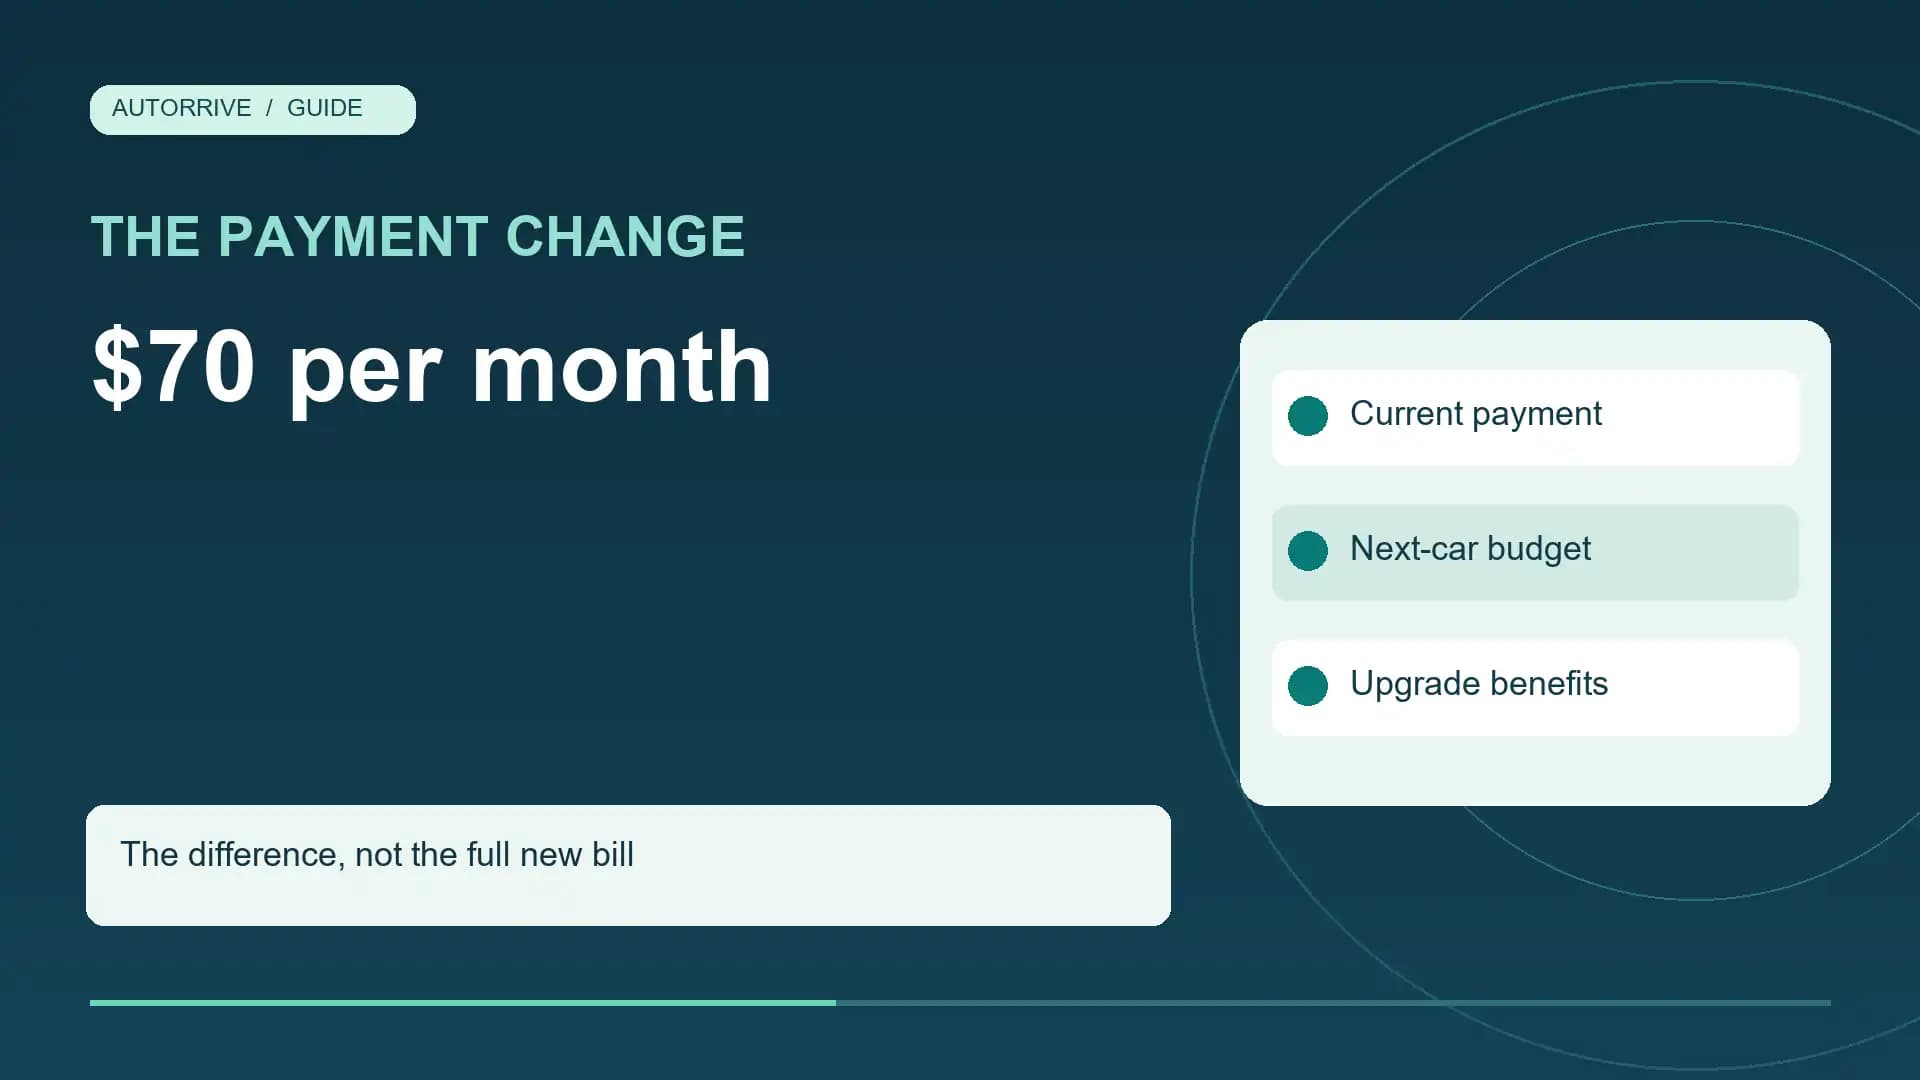
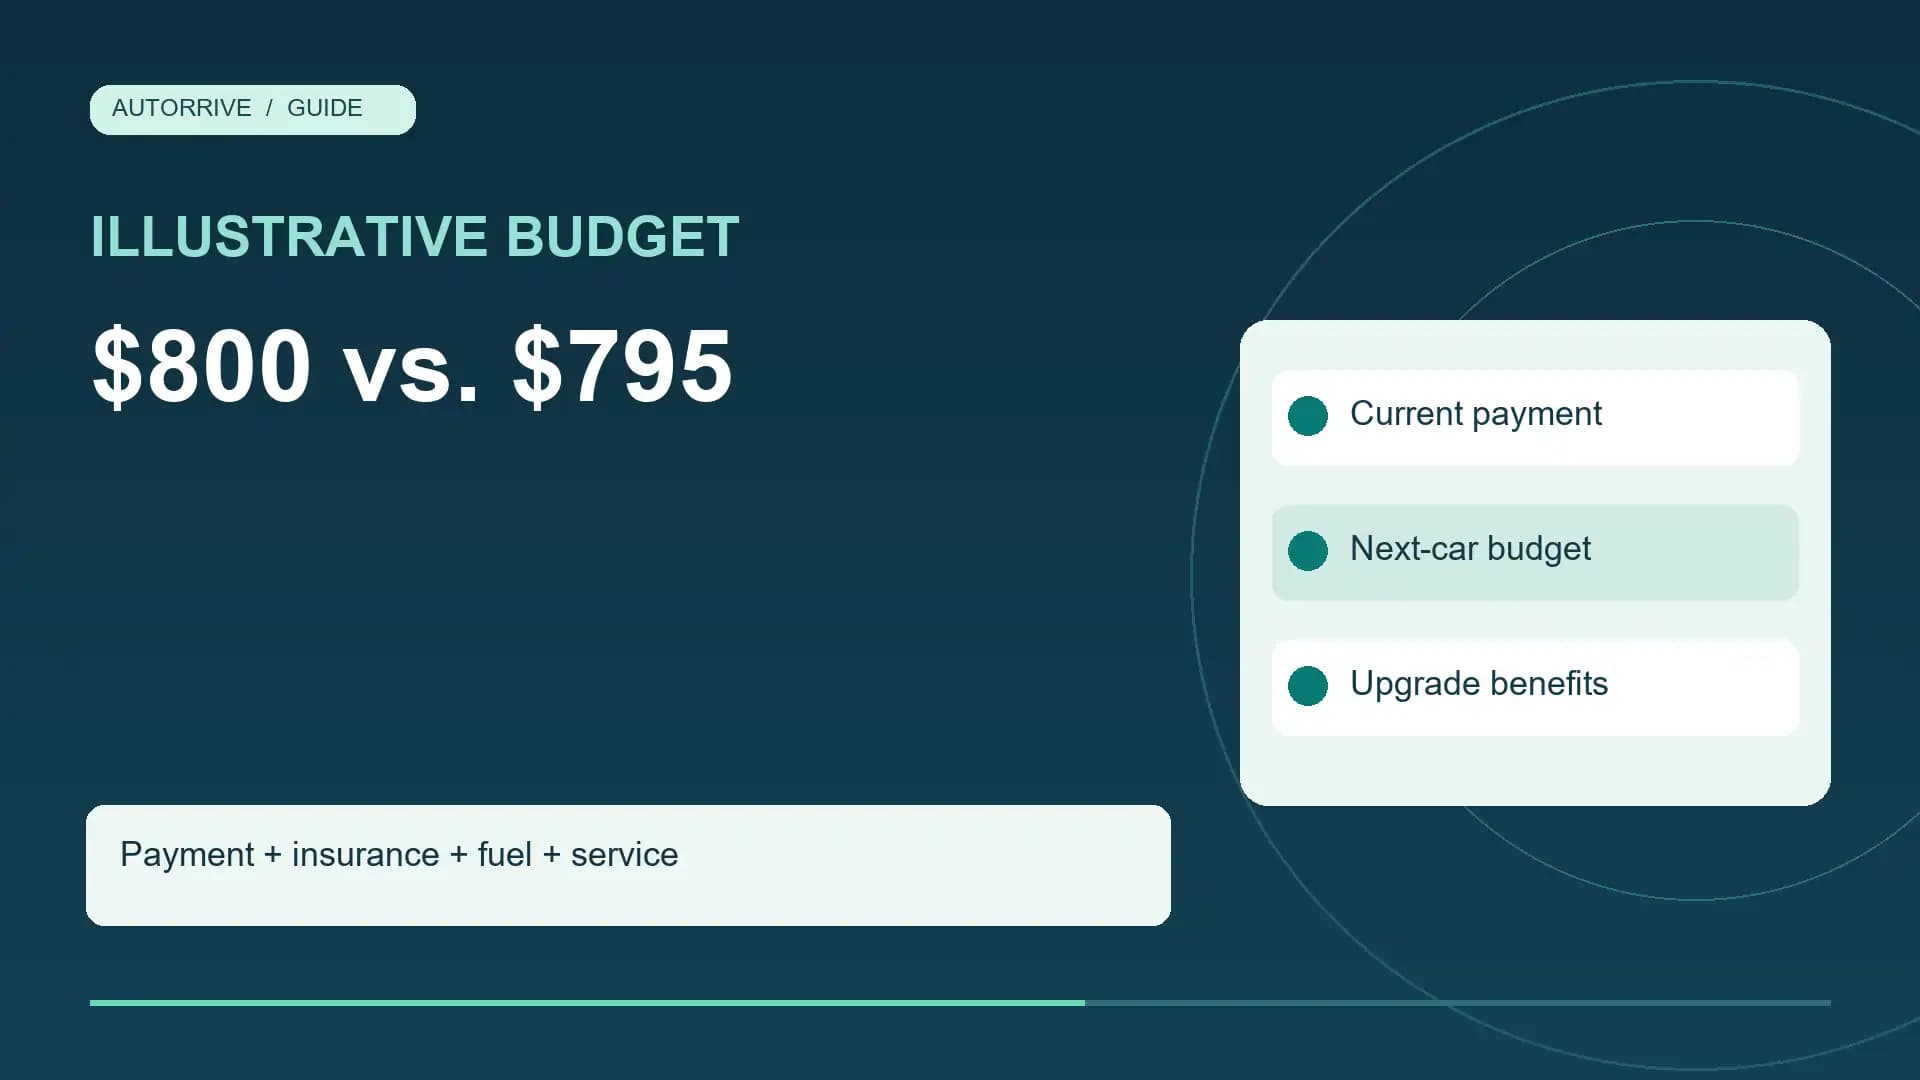
The replacement's payment is $70 higher, but the overall budget in this example is $5 lower because other estimated costs differ. These are planning figures, not a promise that a newer car will save money. Get an insurance quote, use realistic fuel costs, and evaluate the replacement's condition and likely maintenance. A repair reserve spreads an estimated cost across months; it does not mean a service bill arrives monthly.
Also check when your current loan ends. If only six payments remain, count six payments in a twelve-month worksheet, not twelve. A new loan might run for several additional years. The near-term budget and the full borrowing commitment both matter.
Add the costs that happen at purchase
Monthly costs do not capture a down payment, sales tax, title and registration, dealer charges, or debt carried over from the trade. Request an itemized out-the-door quote. Decide which costs you will pay in cash and which enter the amount financed. Do not count a financed fee again as a separate cash payment.
For a twelve-month cash-flow comparison, add the actual payments due during that period, insurance, fuel, expected service, and upfront cash. For a longer ownership comparison, consider depreciation and loan interest as well. Cash flow answers affordability; total ownership cost answers what the vehicle costs over time. Keep those methods distinct to avoid counting both the full purchase price and all loan payments as if they were different purchases.
Know the trade and payoff before choosing the loan
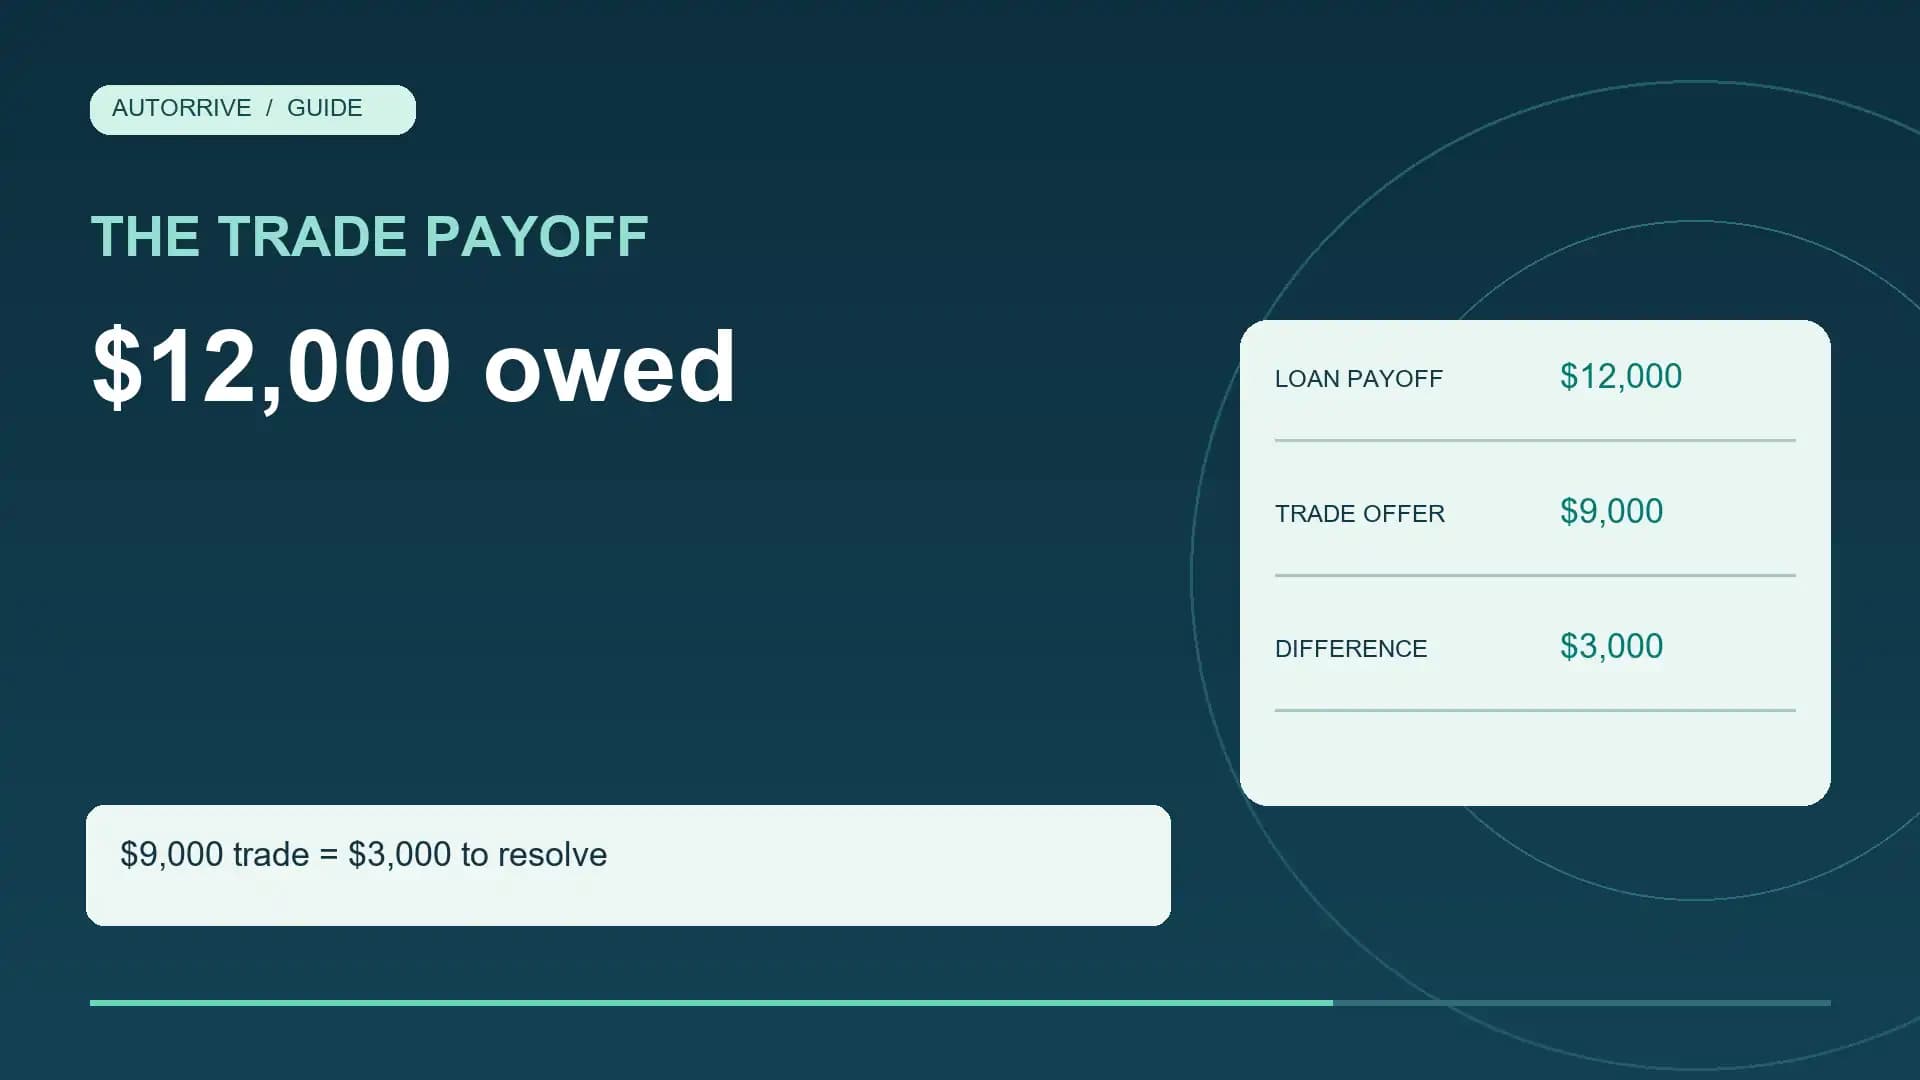
Get a current payoff directly from your lender. Compare it with a written trade offer for the vehicle in its present condition. A $12,000 payoff and a $9,000 trade offer leave $3,000 to resolve. Paying that in cash or financing it changes the new deal. A trade worth more than the payoff creates equity that can support the next purchase.
Ask for the replacement price, trade allowance, payoff, down payment, optional products, and new amount financed on separate lines. A dealer may be able to handle the existing payoff as part of the transaction, but confirm how the difference is funded. Rolling an unpaid balance into the next loan increases the new borrowing and can increase interest and negative equity.
Still deciding which vehicle fits?
Start with your budget, space and everyday needs. Help me decide walks you through the choices so you can narrow down vehicles that fit your life.
Explore vehicles similar to your recent searches, or popular models when you are just getting started.
Price the benefits of the replacement
Reliability matters when a missed commute can cost income or a breakdown can leave family plans stranded. Space and accessibility matter every day. Better-fitting equipment can make driving and parking easier. These benefits can justify an upgrade even if it costs more, provided the complete budget is affordable.
Condition still matters. A replacement may need tires, brakes, scheduled service, or other work. Review records and warranty terms and ask about known issues. When comparing vehicles, use the same out-the-door quote format and evaluate the actual cars rather than an advertised payment.
Use financing to support the right purchase
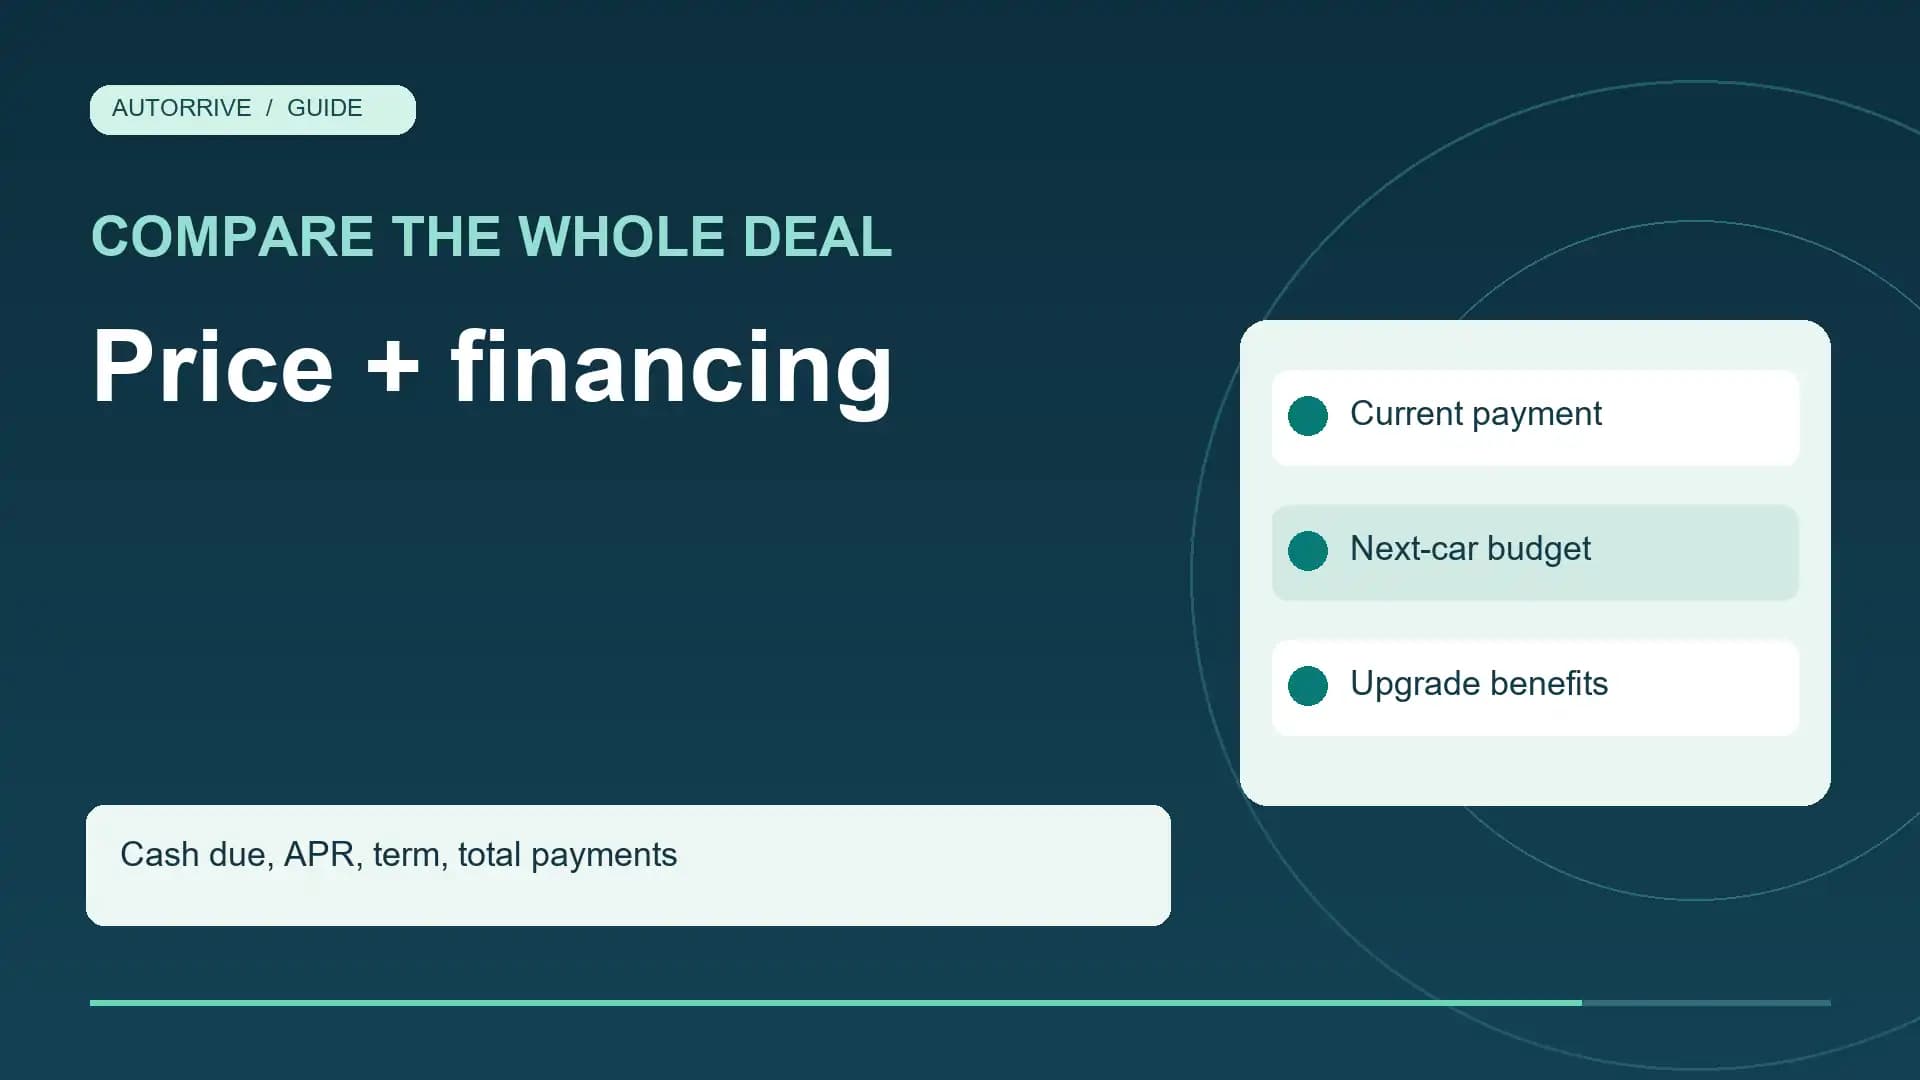
Compare annual percentage rate, amount financed, term, monthly payment, finance charge, and total payments. A longer term can reduce the monthly payment while increasing the time and total amount you pay. Choose a payment that leaves room for insurance, fuel, maintenance, and other household obligations.
If you are financing most of the purchase, consider whether GAP coverage would help with an eligible shortfall after a total loss. Check its price, exclusions, limits, and cancellation terms alongside any protection you already have. Optional products should be individually priced so you can choose what fits your situation.
A practical upgrade plan
Name the improvement you want: reliability, space, comfort, safety equipment, or capability.
Record your current payment, remaining term, payoff, insurance, fuel, and expected service.
Get a trade offer and itemized quotes for vehicles that meet your needs.
Compare the complete monthly budget, upfront cash, and total loan commitment.
Test drive the finalists and verify the equipment and written deal.
Frequently asked questions
Can buying a newer car improve my budget despite a higher payment? Yes, other costs may be lower. Compare insurance, fuel, service, upfront costs, and the loan term. Savings depend on the actual vehicles and your use.
Should the current loan payment be in the comparison? Yes. Count the payments actually due during the comparison period. If the current loan ends sooner, account for that.
Can I buy another car while I still owe on mine? Often, subject to the transaction and lender's terms. Get the payoff and trade offer first so equity or an unpaid difference is visible.
Is the lowest monthly payment the best offer? Not necessarily. Compare the vehicle's fit, out-the-door price, annual percentage rate, term, and total payments.
Next step: Choose what the next car needs to improve, then compare two actual vehicles against the complete budget you already have.
Next car priorities include room, comfort, and reliability
Current $350 payment compared with $420 replacement payment
The increase in loan payment is $70 per month
Illustrative monthly budgets of $800 and $795
A $12,000 payoff and $9,000 trade leave $3,000 to resolve
Compare price, cash due, APR, term, and total payments
Test the actual car for the improvements you need
A practical visual guide
Explore the inventory
Vehicles related to your search
Explore vehicles similar to your recent searches, or popular models when you are just getting started.