Two cars look nearly identical. The first is advertised at twenty-four thousand dollars, plus an eight-hundred-dollar dealer fee. The second is twenty-four thousand seven hundred dollars, plus a two-hundred-dollar fee. Before the same tax assumptions, the first is one hundred dollars cheaper. Now add a required five-hundred-dollar product to the first quote. The order flips. That is why the advertised number alone cannot settle the comparison. Request an itemized out-the-door quote for the exact vehicle identification number and your registration location. Keep the selling price, government charges, dealer charges, required accessories, and optional products on separate lines. Ask which discount conditions you actually meet. Show the trade and its payoff separately so a favorable trade number does not disguise a higher car price. Then compare financing by annual percentage rate, term, amount financed, and total payments. At signing, match the contract to the quote. If a new fee appears, stop and ask for a revised total. The goal is simple: compare the complete purchase you are actually offered.
An advertised vehicle price is a starting point, not the amount you will necessarily pay to drive away. Taxes, title and registration, dealer charges, and optional products can change the total. The clearest comparison is an itemized out-the-door quote for the exact vehicle, with your registration location and any conditions spelled out.
Quick answer: Ask every seller for the vehicle identification number, selling price, each required tax and fee, each optional product, and the final out-the-door total before discussing monthly payments. Compare the total for equivalent vehicles and terms. A fee's label matters less than whether it is mandatory, disclosed, and included in the figure you compare.
What belongs in the quote
The out-the-door price usually means the vehicle selling price plus applicable taxes, title and registration, and dealer charges required to complete the purchase, less applicable discounts. Local rules and tax treatment differ. If a trade or financing is involved, ask for both a vehicle-only total and a separate worksheet showing the trade allowance, payoff, down payment, and amount financed. Loan interest accrues over time and is not part of a simple cash out-the-door total.
What belongs in the quote
Line
What to verify
Vehicle price
Exact VIN, trim, equipment, mileage, and sale conditions
Government charges
Tax, title, registration, and location used
Dealer charges
Documentation, processing, delivery, preparation, or other required items
Optional items
Service contract, protection, accessories, GAP, and whether they are already installed
Discounts
Eligibility, financing or trade conditions, and expiration
Final total
Amount due before financing and any trade payoff
A dealer charge may be permitted and still affect the comparison. “Required” does not mean government-imposed. Ask who receives the fee and whether it can be removed or offset in the selling price. State laws on disclosure and limits vary, so avoid assuming a fee is illegal solely from its name.
The lower advertised price can cost more
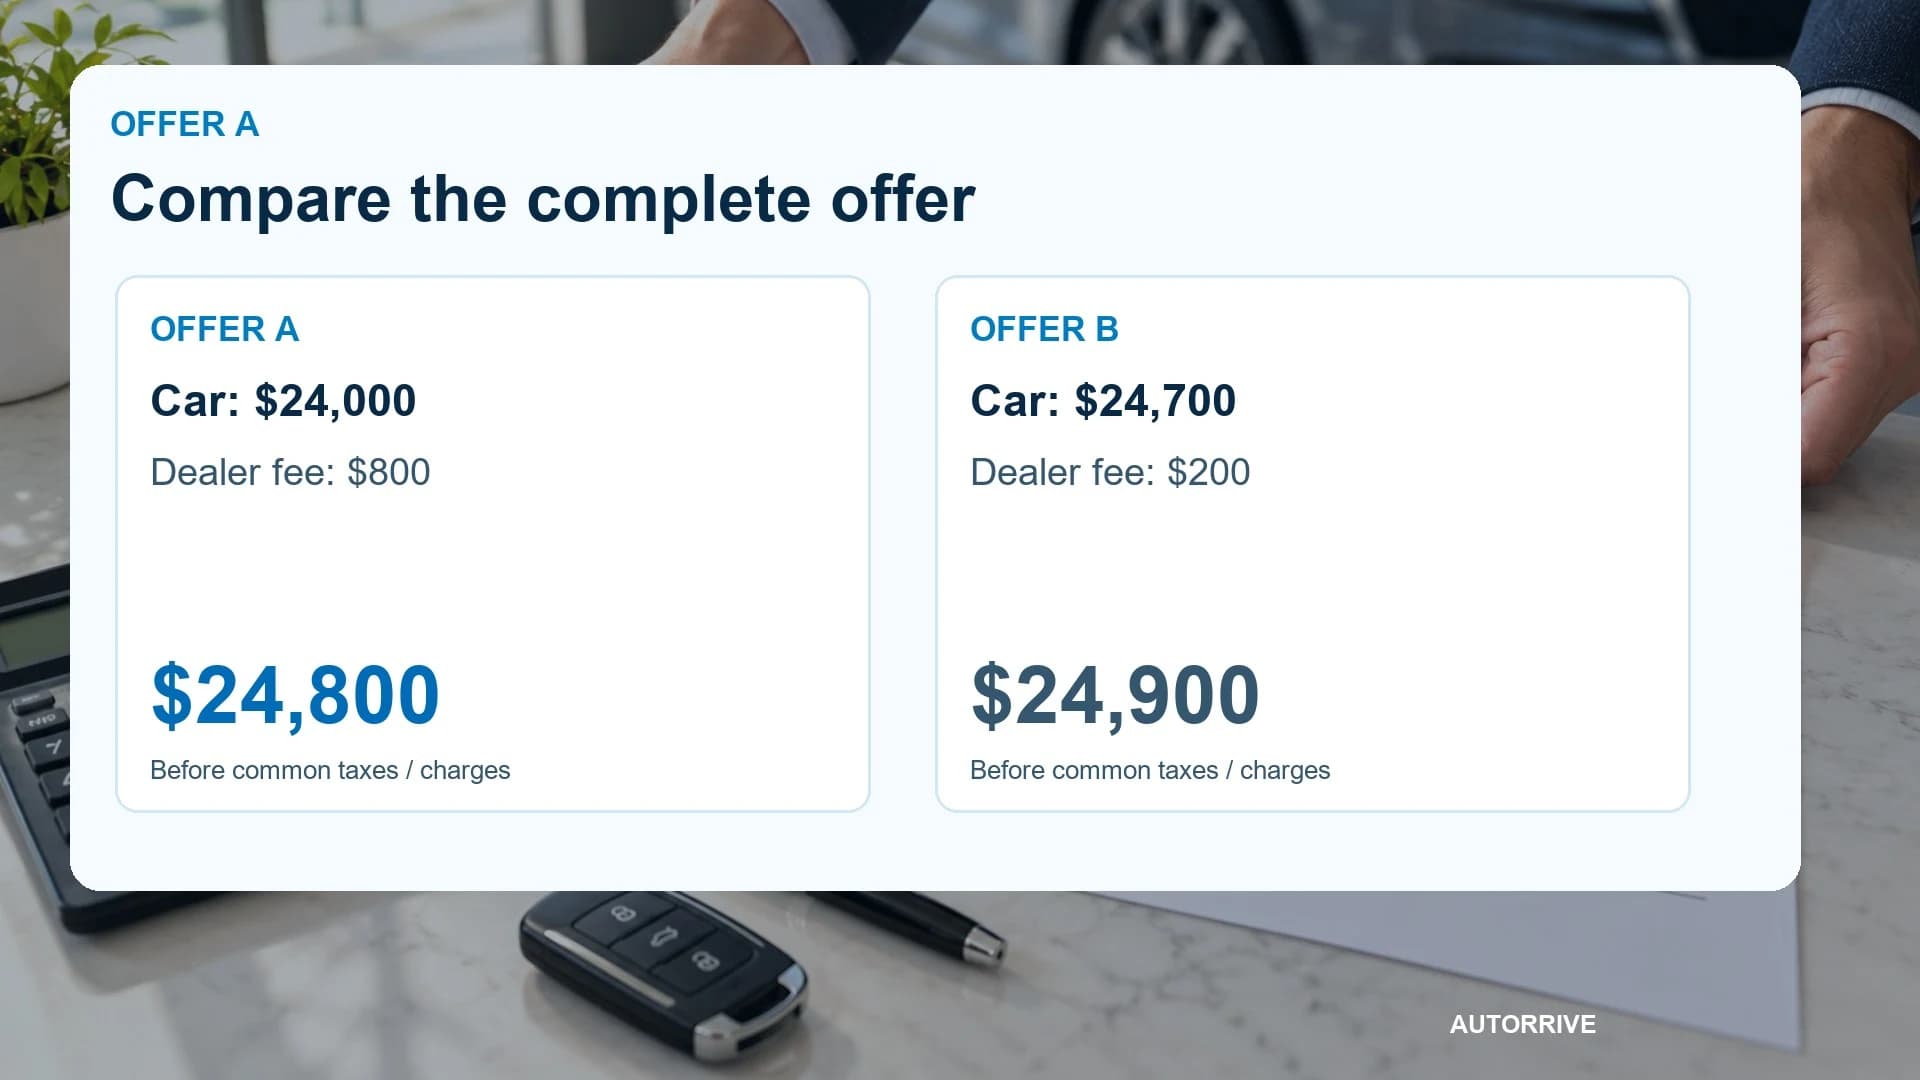
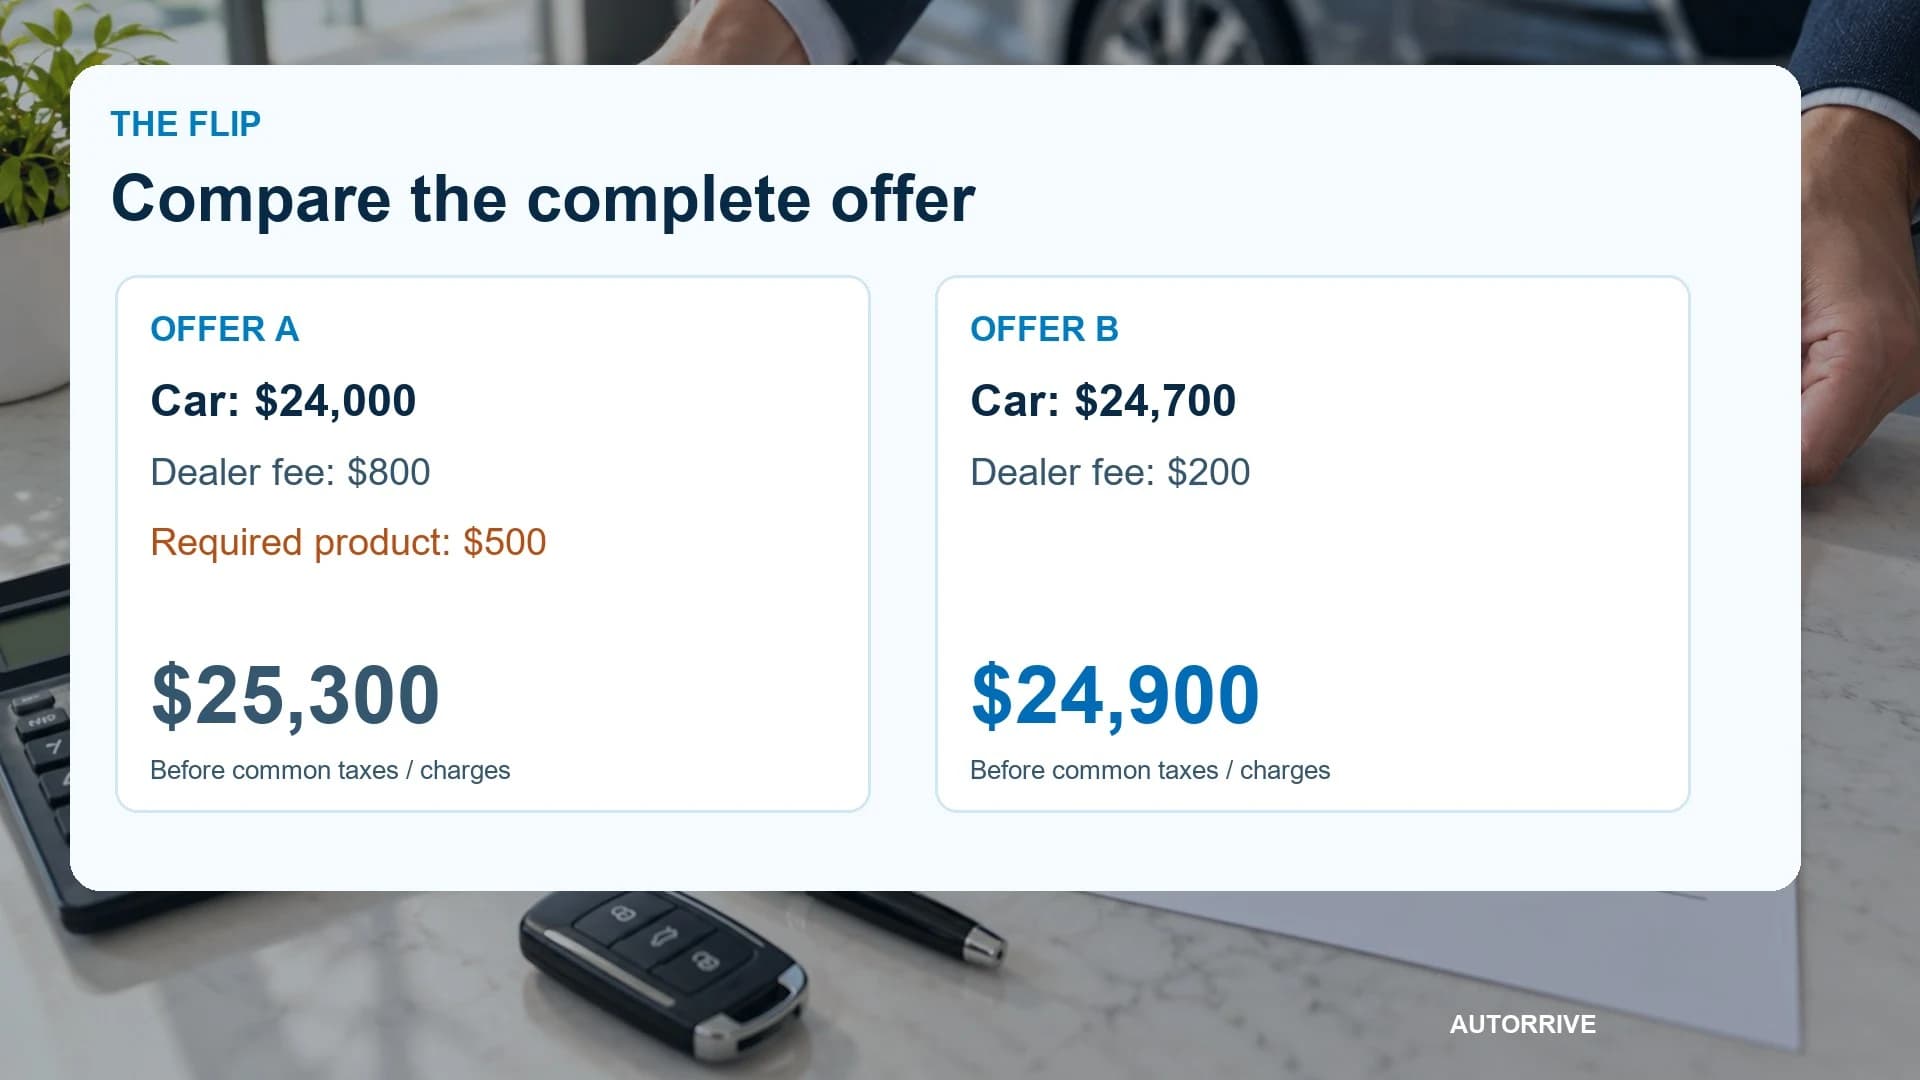
Dealer A advertises $24,000 and has an $800 dealer fee. Dealer B advertises $24,700 and has a $200 fee. Before the same tax and registration assumptions, A totals $24,800 and B totals $24,900. A is still $100 lower in this simplified case. Change A's required add-ons by $500, however, and B becomes the lower total. The point is to do the addition, not to declare one kind of fee automatically good or bad.
When comparing quotes, keep the vehicle, timing, tax location, and incentive eligibility as similar as possible. A quoted price contingent on dealer financing, a trade, or a rebate you do not qualify for is not your price. Ask the seller to revise the quote with your real circumstances.
Watch how optional products enter the total
A service contract, maintenance plan, protection treatment, accessory, or GAP product can be valuable to a particular buyer, but price each separately. Ask whether it is optional, what it covers, who administers it, and what happens if you cancel. If an item is already on the car, ask whether its cost is included in the advertised price or added later. Do not infer that an optional product is required for financing without checking the lender's written terms.
Financing can make a $900 addition look small per month while you also pay interest on the larger balance. Keep a copy of the itemized quote and compare it with the buyer's order and retail installment contract. If the numbers change, stop and resolve the difference before signing.
Still deciding which vehicle fits?
Start with your budget, space and everyday needs. Help me decide walks you through the choices so you can narrow down vehicles that fit your life.
“Please send an itemized out-the-door quote for VIN [number], registered in [ZIP code]. Show the selling price, all taxes and government charges, each dealer charge, required accessories or products, any optional products separately, discounts and their eligibility, and the final total. Please show trade and financing separately.”
A written quote also makes it easier to compare sellers without losing track of a verbal promise. If the car is no longer available, request the VIN of the alternative before treating the new offer as comparable.
Before you sign
Verify the VIN, selling price, taxes, fees, optional products, trade value, payoff, down payment, amount financed, APR, term, payment schedule, and total of payments. Check that products you declined are absent. Keep copies of the signed documents. If financing is not final at delivery, understand the written conditions before taking the car.
Frequently asked questions
Is a documentation fee the same as tax? No. A document or processing fee is generally a dealer charge; tax and registration are government charges. Both can affect the total.
Can I negotiate a fee? Ask whether it can be removed or offset through the vehicle price. The result and any limits depend on the seller and applicable rules. Negotiate the complete price you will pay.
Does out-the-door include loan interest? Usually it describes the purchase transaction total before the interest paid over a loan. Compare loan offers separately using APR, term, and total payments.
What if a fee appears only at signing? Ask for an updated itemized total and compare it with the earlier quote. You can pause before signing to understand the change.
Next step: Request the same itemized quote format from each seller. Compare final totals first, then compare financing on the same amount and term.
First offer totals $24,800 before common charges
Second offer totals $24,900 before common charges
A $500 required product raises the first offer to $25,300
Request an itemized quote for the exact VIN and location
Keep the vehicle price, trade, and loan on separate lines
Match the signing contract to the written quote
A practical visual guide
Explore the inventory
Vehicles related to your search
Explore vehicles similar to your recent searches, or popular models when you are just getting started.