Buying a car should open up possibilities: easier commutes, weekend adventures, and family trips you have been looking forward to. An unexpected repair can interrupt those plans. An extended service contract can help you manage that risk by paying for eligible repairs under the agreement.
You may value an extended service contract if a repair bill of several thousand dollars would disrupt your budget and you want the reassurance of coverage. The right choice depends on the car, any warranty it already has, and the protection the contract actually provides. Coverage is optional, and benefits vary by plan.
What does an extended service contract do?
An extended service contract is an agreement to pay for specified vehicle repairs or services during a defined period. People commonly call it an “extended warranty,” although a separately purchased service contract is different from a manufacturer's warranty.
It is similar to insurance in one practical sense: you arrange protection against the financial impact of an unexpected event. The comparison helps explain the purpose; it does not mean that every service contract is legally an insurance policy or has identical rules.
The agreement defines eligible failures, covered components, the coverage period, deductibles, exclusions, and claim procedures. Some plans cover a narrower list of parts. Others offer broader protection with a list of exclusions. Read the actual agreement rather than relying on a label such as “comprehensive.”
Covered repairs and routine maintenance are different
A contract may cover an eligible mechanical breakdown involving an engine, transmission, or another listed system. It generally does not turn all car expenses into covered expenses. Oil changes, routine servicing, and normal wear items may be excluded unless a specific benefit includes them.
Maintenance requirements matter, too. Keep service records and follow the agreement's requirements. A pre-existing problem or an excluded cause of damage may fall outside coverage even when the affected part appears in the plan.
Understand the different kinds of car coverage
The word “warranty” can describe several protections. Start with what already comes with the car, then compare any additional service contract.
| Type of coverage | What it generally addresses | What to confirm |
|---|---|---|
| Factory basic or comprehensive limited warranty | Eligible defects across a broader range of vehicle systems | Covered components, exclusions, original start date, and remaining coverage |
| Powertrain warranty | Specified major drivetrain components, often including the engine and transmission | The exact parts covered; it does not automatically include every electrical or comfort feature |
| Used-car or certified pre-owned limited warranty | The protection specifically offered with that vehicle or certification program | Written coverage, repair-cost responsibility, start date, and time and mileage limits |
| Optional extended service contract | Eligible repairs under an additional purchased agreement | Coverage level, claim administrator, deductible, repair authorization, and included travel benefits |
Warranty periods often have both a time limit and a mileage limit, with coverage ending when the first applicable limit is reached. Use the actual agreement for the car you are buying. Existing coverage may transfer or have conditions; confirm its status rather than assuming a used car has no protection or full new-car coverage.
Listed-component and broader coverage plans
A listed-component plan covers the parts specifically named in the agreement. A powertrain-focused plan may protect a narrower set of major mechanical components. A broader exclusionary plan describes coverage with a list of exclusions. Even a plan marketed as “bumper-to-bumper” can have exclusions, so the written terms matter more than the label.
The terms that shape a claim
- Coverage start and end: Check the start date, elapsed time and mileage rules, and any waiting period. Ask whether mileage is measured from the current odometer or a stated total limit.
- Deductible: Confirm your share of an approved repair and whether it applies per visit or per repair.
- Covered failures and exclusions: Review the covered parts, excluded causes, routine maintenance and normal wear rules, and any pre-existing-condition provisions.
- Repair authorization and payment: Know which facilities are eligible, who approves work, and whether the administrator pays directly or reimburses you.
- Extra benefits and limits: Towing, rental transportation, and trip interruption may have separate conditions, allowances, and receipt requirements.
With those basics in mind, here is how suitable coverage could help on a family trip.
A family vacation—and an unexpected breakdown
Picture a family picking up their next car, packing the bags, and heading toward the mountains. Everyone is excited. A few days into the trip, the car develops a problem and will not continue safely. They pull into a safe turnout and call for help.
A tow truck takes the car to a repair shop. The diagnosis comes with a repair estimate of $3,400. That is an illustrative example, but some major mechanical repairs really can cost thousands of dollars. A large bill is difficult enough at home; away from home, there are transportation and accommodation arrangements to make as well.
The father gives the shop the family's extended service contract information. The shop contacts the administrator, follows the claim process, and gets approval for a covered repair. Depending on the agreement, the administrator may pay the shop directly, leaving the family responsible for a deductible and any expenses the contract does not cover. A covered repair can mean little or no out-of-pocket repair expense when the plan's terms allow it.
Their plan also includes eligible towing, rental transportation, and trip interruption benefits. A rental car arrives, they load their bags, and they continue with the parts of their trip that are still practical. The car remains at the shop for the approved repair. The contract helps turn an expensive disruption into a more manageable problem.
That outcome depends on the actual contract. A rental car, direct payment, travel reimbursements, and a zero-dollar deductible are not automatic benefits of every plan. The story illustrates what suitable coverage can do when its conditions are met.
Help beyond the repair bill
A breakdown away from home can create several costs at once. Useful benefits may extend beyond the work performed in the repair bay.
| Benefit | How it can help | What to check |
|---|---|---|
| Towing or roadside assistance | Helps get a disabled car to an eligible repair facility | Covered events, destination rules, distance or dollar limits, and how to request assistance |
| Rental transportation | Helps you get around while an eligible repair is completed | Authorization, daily and total limits, eligible rental days, and payment or reimbursement arrangements |
| Trip interruption | May reimburse eligible meals, lodging, or transportation when a covered breakdown interrupts travel | Required distance from home, overnight requirements, covered expenses, receipts, and benefit limits |
| Direct repair payment | An administrator may pay an approved repair facility directly | Shop participation, authorization, deductible, and any charges you must pay |
These benefits can reduce the work of finding and paying for help during a stressful interruption. They can also make it easier to keep some of your travel plans. They do not guarantee that someone will arrange every detail for you: ask who makes reservations, who pays initially, and which expenses require reimbursement.
Could coverage give you peace of mind?
Think about the financial risk you want to reduce. If a several-thousand-dollar repair would compete with important household expenses, eligible repair coverage may offer welcome reassurance. If you regularly travel with your family, towing and travel benefits may make the agreement more useful to you.
The goal is to choose protection that fits the vehicle and your needs. Consider how long you expect to keep the car, the mileage you drive, and whether existing warranty coverage overlaps with the contract. Ask when the additional coverage starts and when it ends. A plan can be useful without covering every possible expense, as long as you understand what it does cover.
Seven questions to ask before choosing a contract
- Which repairs and components are covered? Request the agreement and its exclusions, including any special rules for the type of car you are buying.
- When does coverage begin and end? Confirm dates, mileage limits, and any waiting period. Check whether existing factory coverage overlaps.
- What deductible applies? Ask whether it applies per visit or per repair and whether the amount changes by repair facility.
- Who administers claims? Save the administrator's contact details and instructions for getting help after hours or away from home.
- Where can the car be repaired? Confirm eligible facilities and whether an approved shop near your travel destination can handle a claim.
- What travel benefits are included? Check towing, rental transportation, meals, lodging, limits, receipts, and authorization requirements individually.
- How are approved repairs paid? Understand direct payment versus reimbursement, any diagnostic or teardown charges, and your responsibility for excluded work.
Review the price and payment arrangement alongside these benefits. Ask for clear written terms so you can choose coverage confidently with your vehicle purchase.
What to do if you break down
Move to a safe location if possible and contact the appropriate assistance service. Have your contract number and administrator's phone number ready. Before authorizing repair work, ask the repair facility to follow the contract's claim and approval process.
Keep the estimate, approval information, repair invoice, and receipts for eligible towing, rental, lodging, or meals. Ask which expenses are approved before spending money you expect to be reimbursed. Following the process helps avoid preventable claim problems.
Common questions about extended warranties
Is an extended warranty required when I buy a car?
An optional extended service contract is a separate choice. Decide whether its coverage and terms address the repair risk you want to manage.
Can a service contract cover a repair costing thousands?
Yes, a covered repair can involve a substantial bill. Payment remains subject to the agreement's covered failures, authorization rules, limits, exclusions, and deductible.
Will I have no out-of-pocket repair expense?
Some approved repairs may leave you with little or no out-of-pocket repair expense. Others require a deductible or payment for excluded charges. Check the agreement before assuming a repair is fully paid.
Does it include towing and a rental car?
Some contracts include these benefits; others do not. Even when included, daily allowances, distance limits, covered-repair conditions, and approval requirements may apply.
What is trip interruption coverage?
It is a benefit that may help pay eligible travel expenses after a covered breakdown away from home. Depending on the plan, these can include meals, lodging, or transportation while the repair is completed.
Can I use it at a repair shop while traveling?
That depends on the agreement's facility and authorization rules. Confirm the process before your trip, and contact the administrator before repair work begins.
Choose your car—and protection that fits your plans
A suitable extended service contract can help you enjoy your next car with greater confidence. If reducing the risk of a large unexpected repair bill matters to you, compare the actual coverage, claim process, and travel benefits. Knowing how the plan works before a breakdown makes its protection easier to use when you need it.
Enjoying the trip
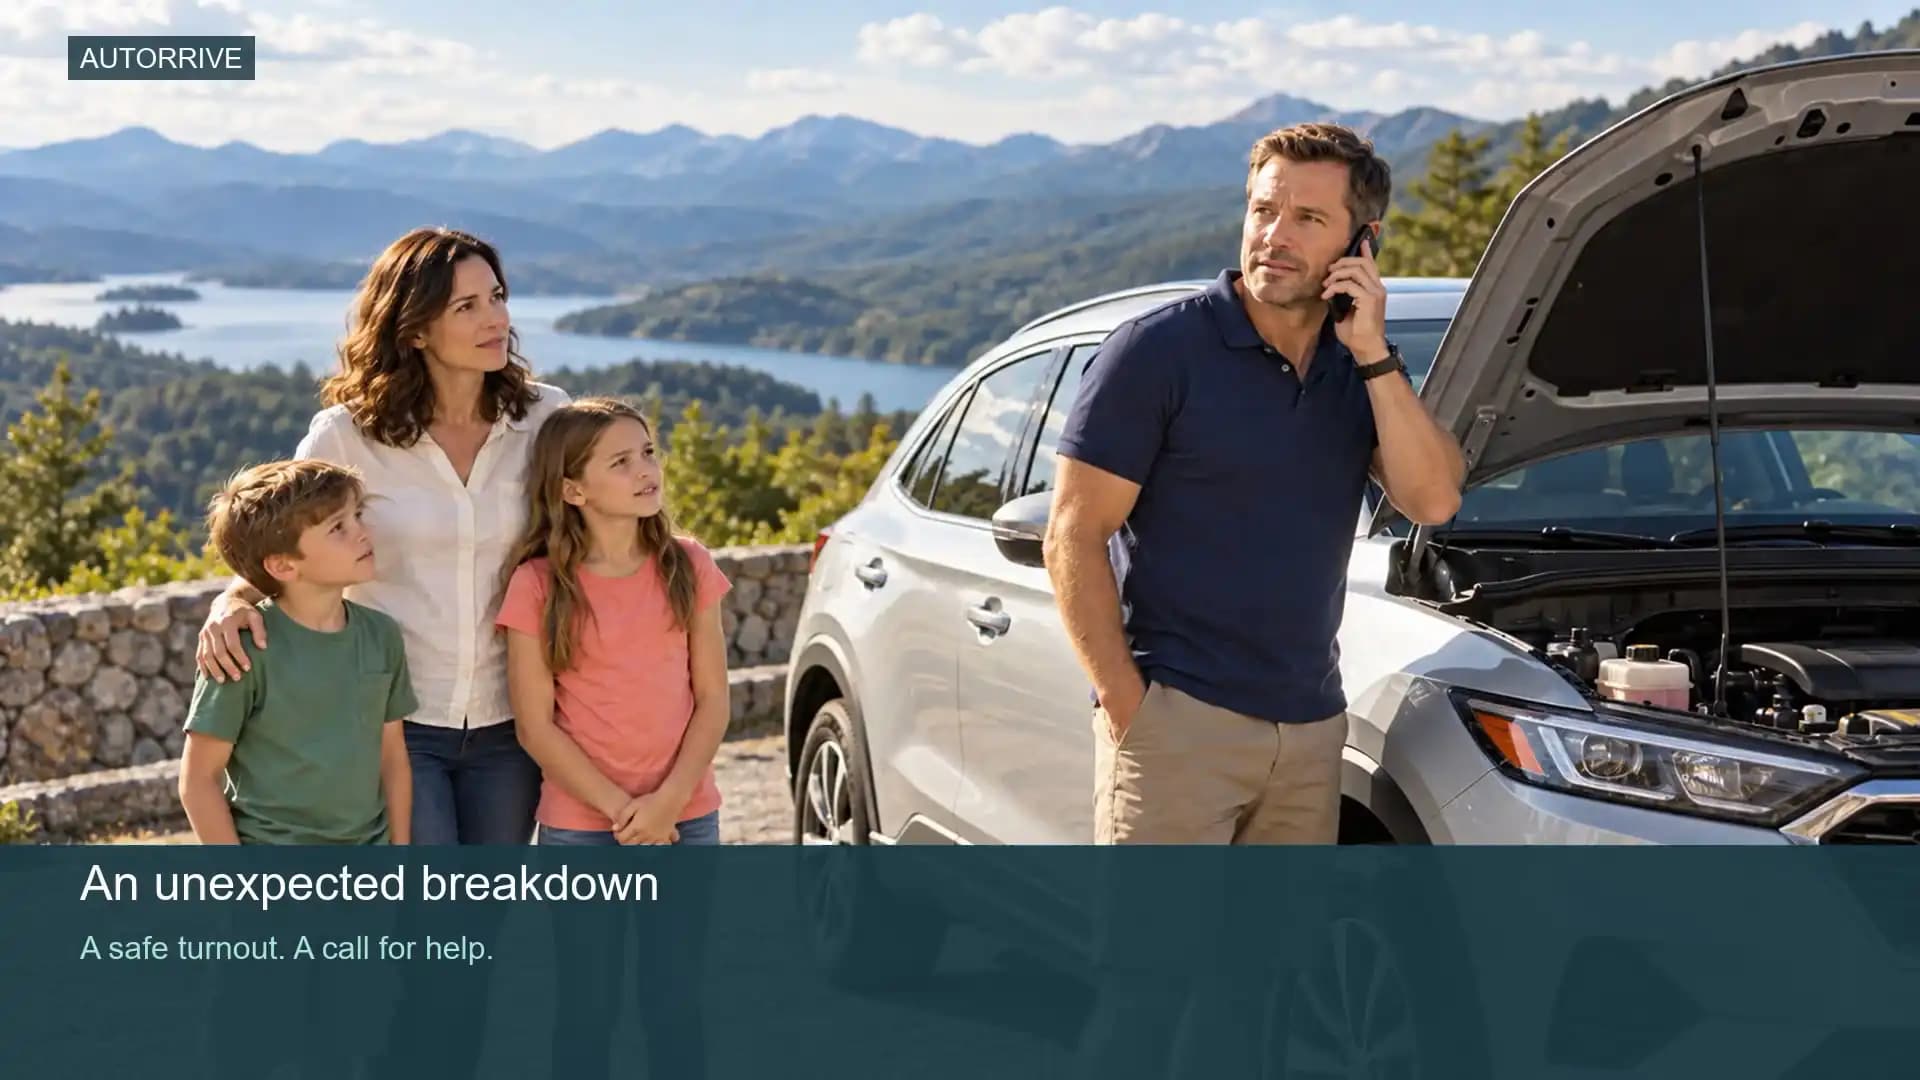
Unexpected breakdown
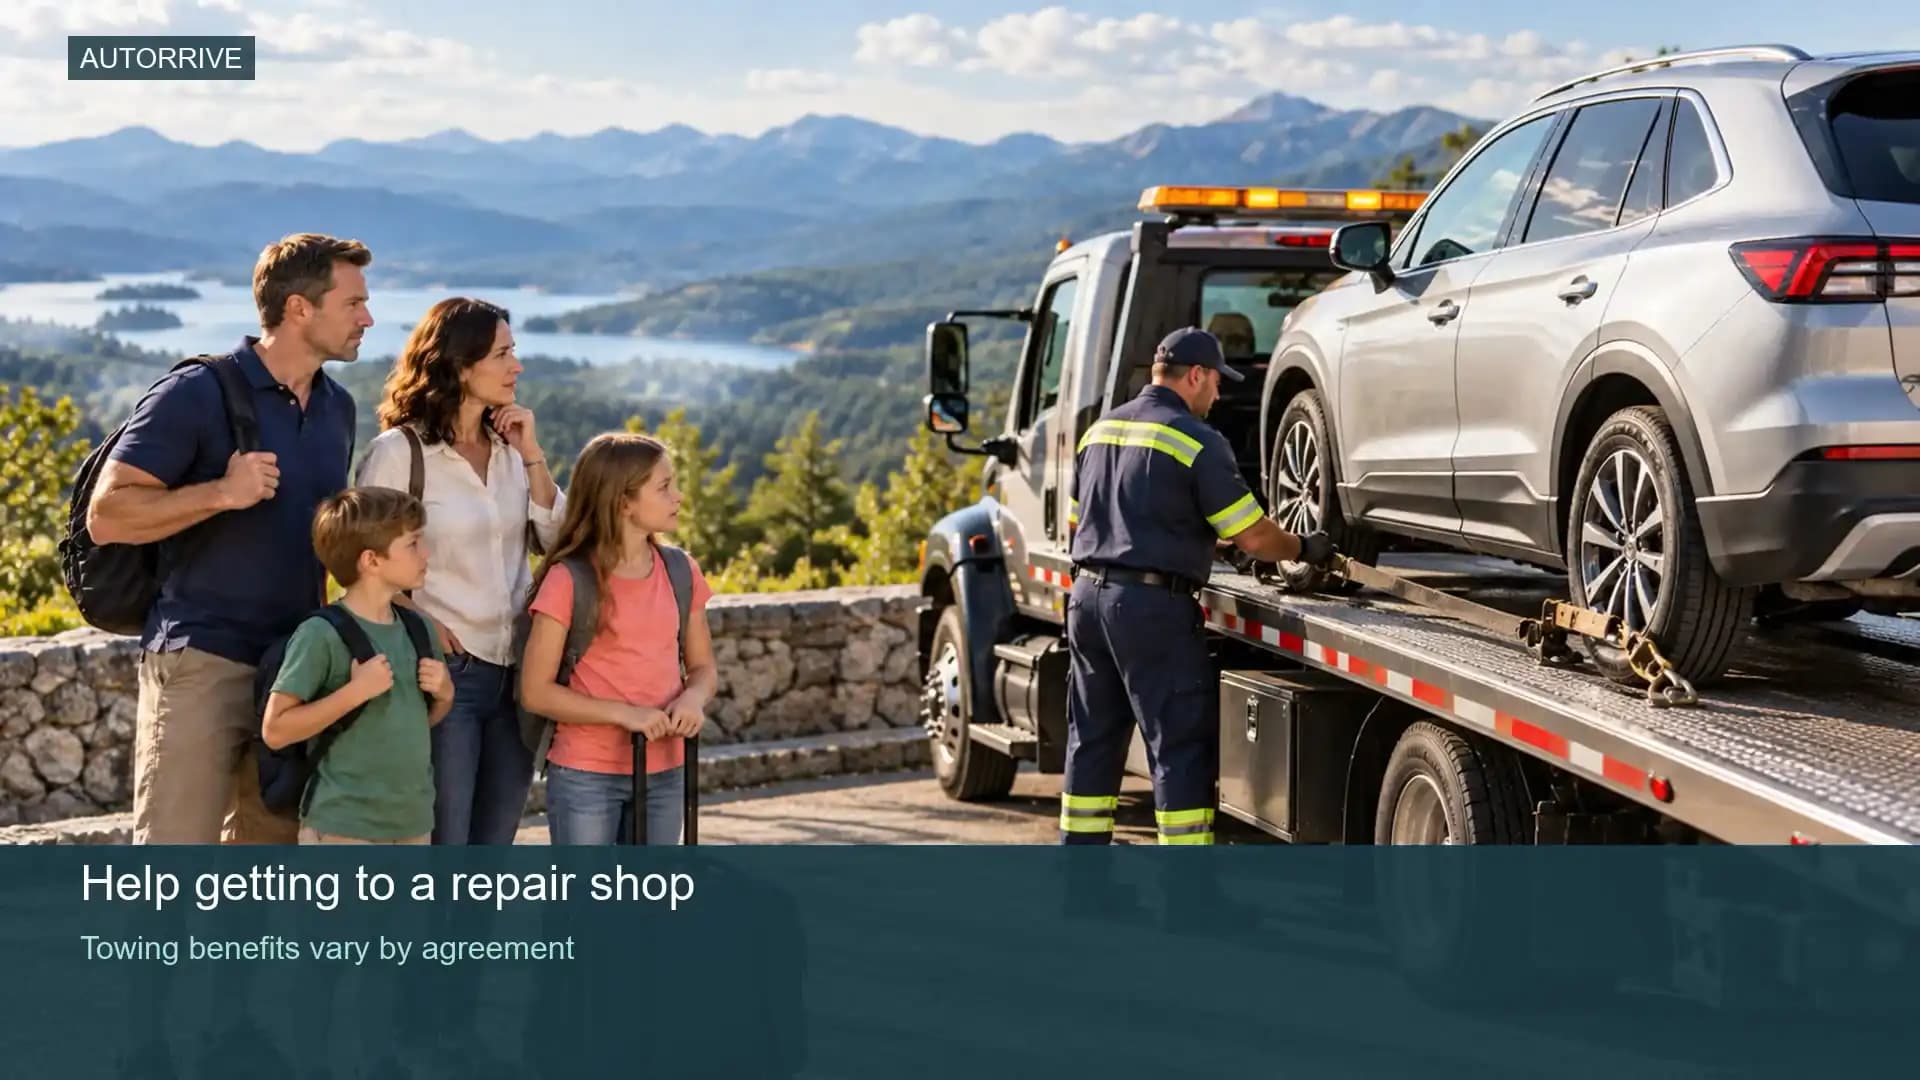
Towing help
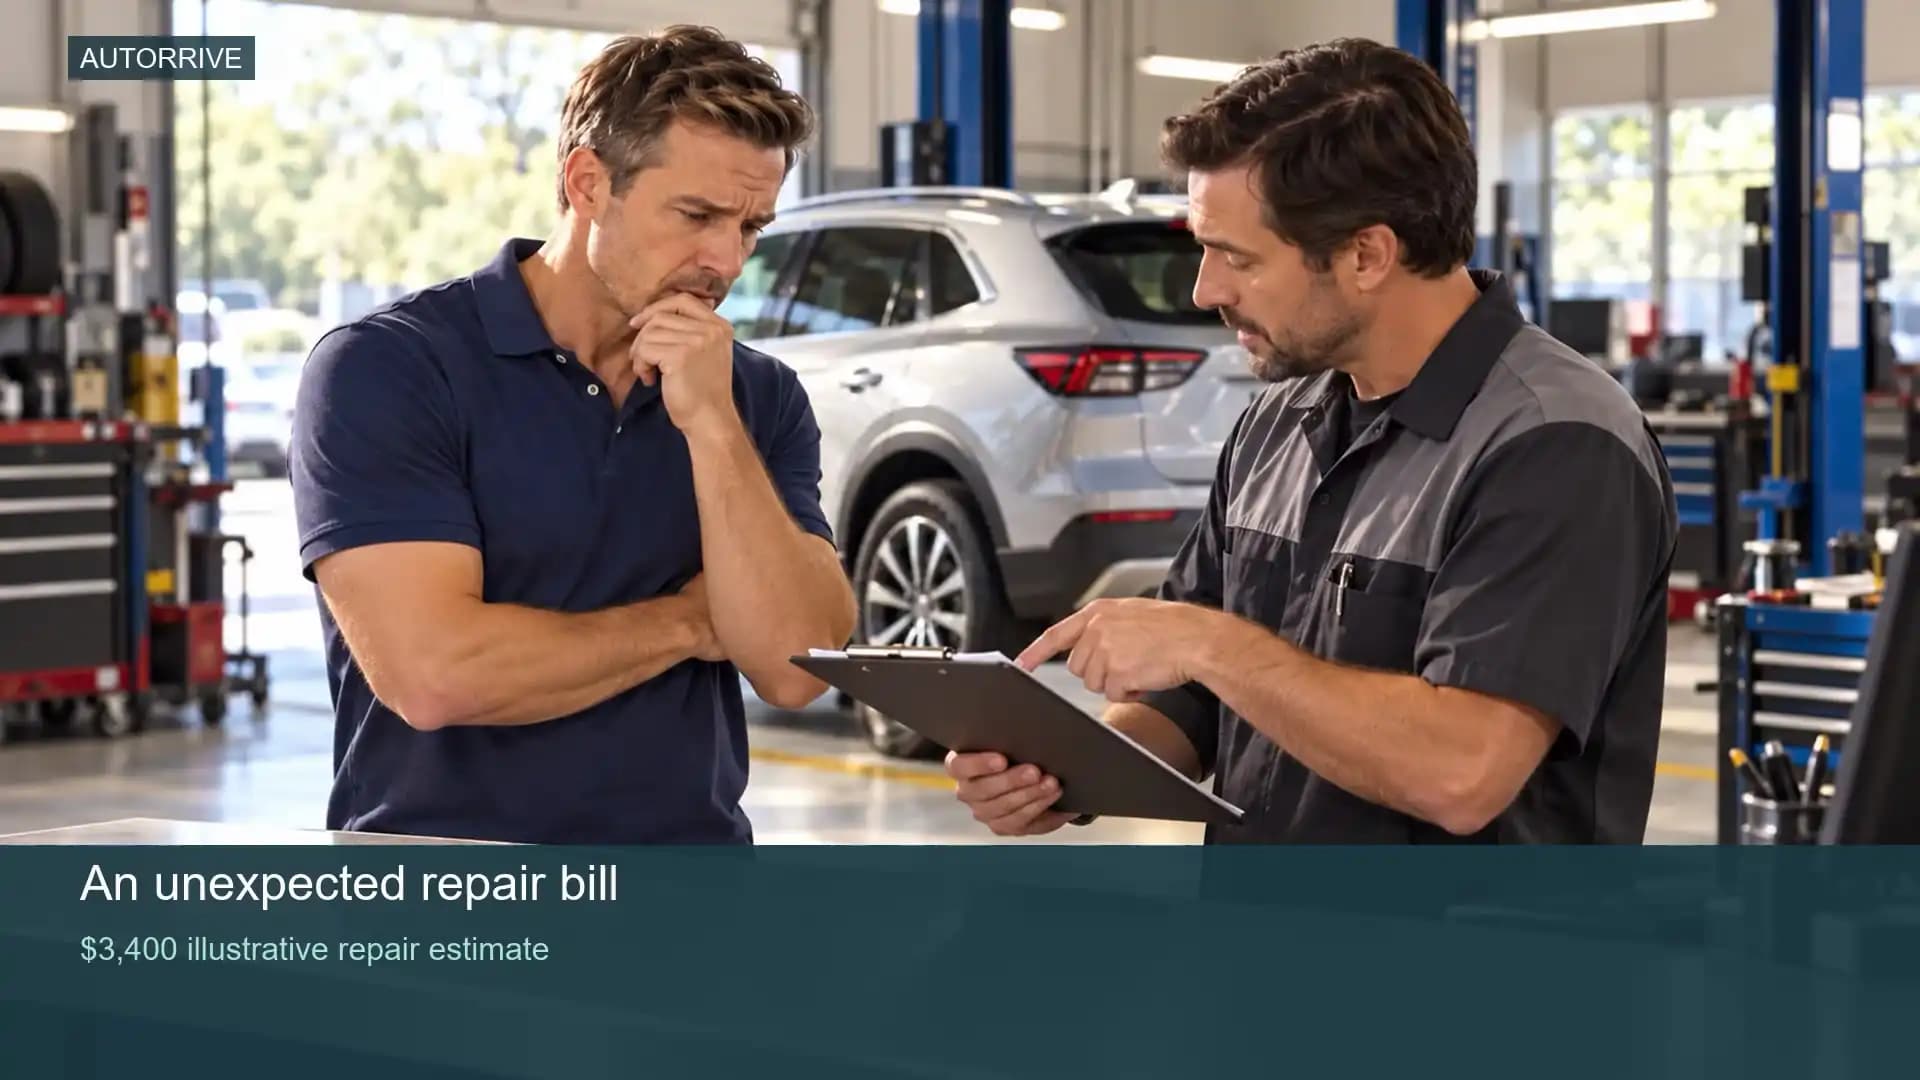
Repair estimate
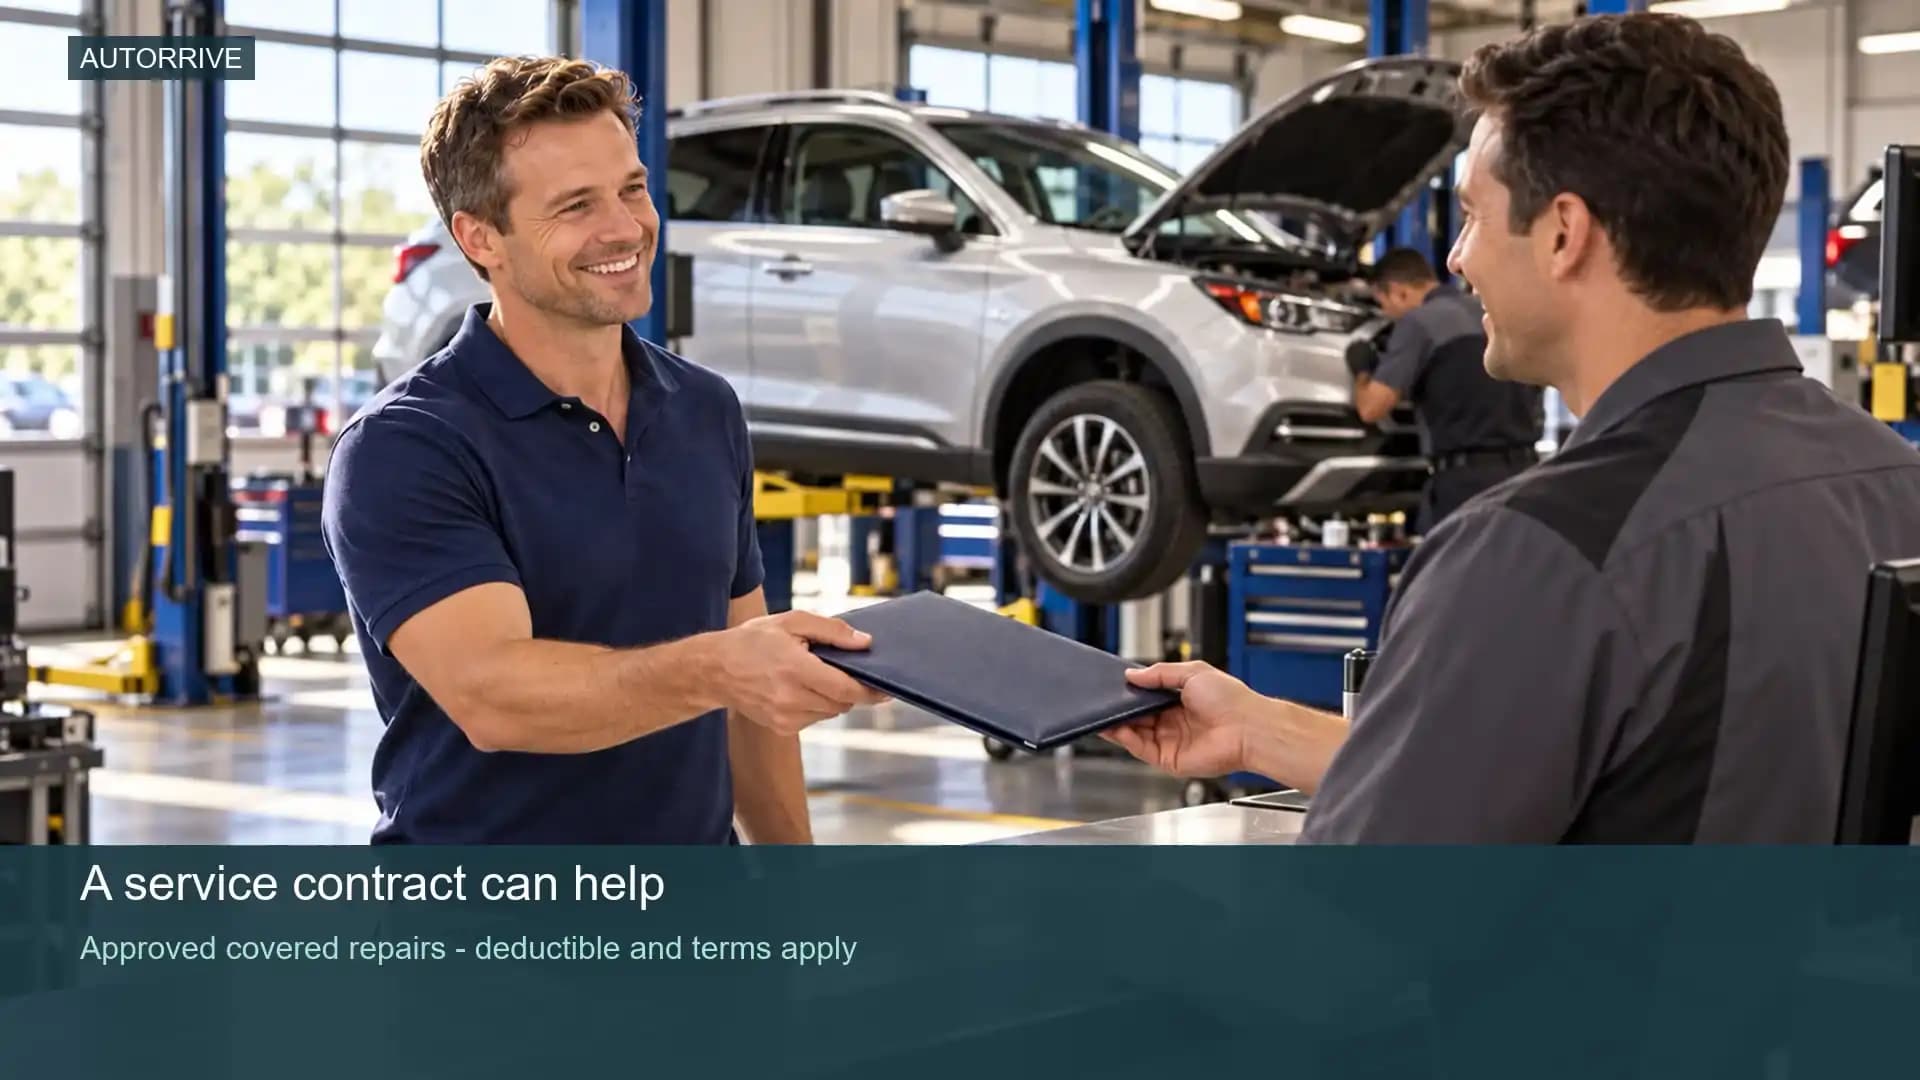
Covered repair approval
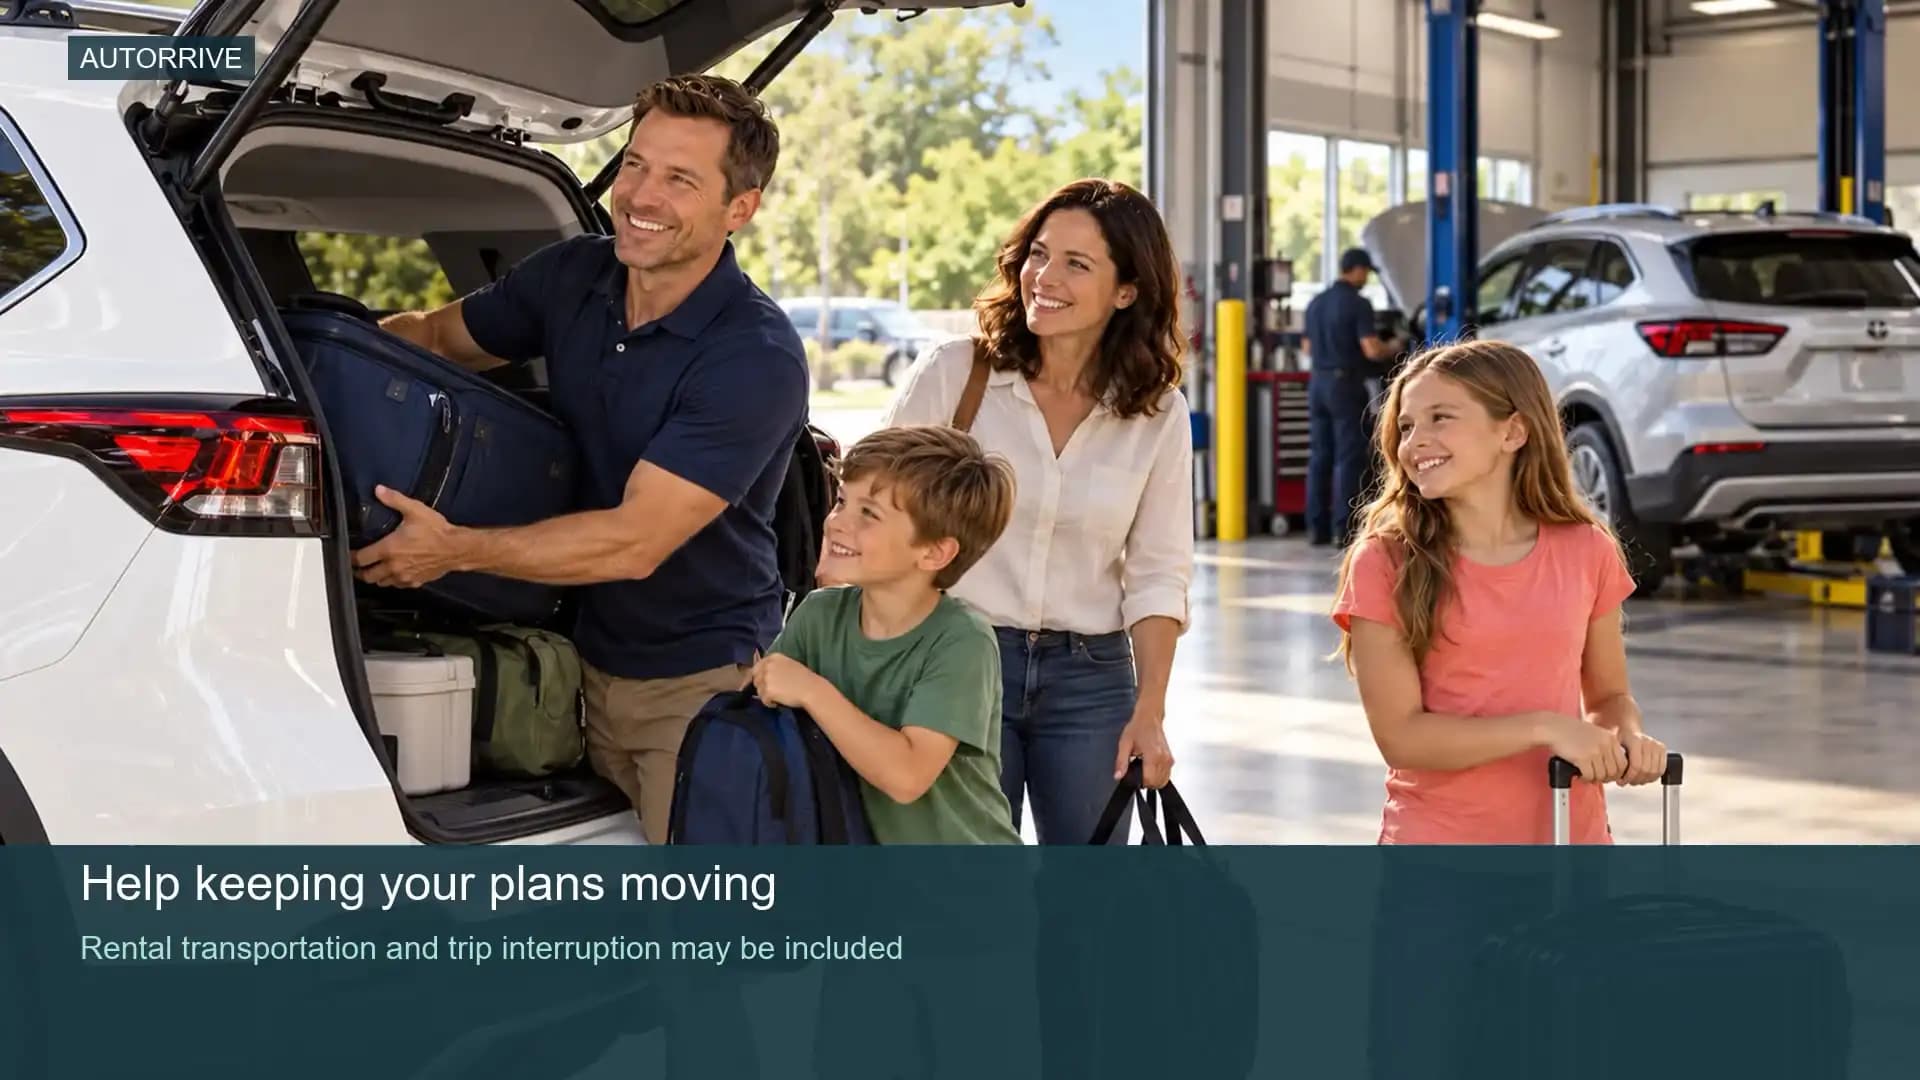
Continuing with a rental